- The call wall requires positive net GEX at or above spot.
- The put wall requires negative net GEX at or below spot.
- Dollar exposure measures modeled hedge sensitivity per 1% spot move.
- A wall crossing alone does not establish a reversal or breakout outcome.
A three-pass reading checklist
Locate it. Check the snapshot. Observe the interaction.
- 01 / LOCATION
How far from price?
Record spot, the wall strike and their distance. A nearby level gives you a specific place to inspect; proximity does not assign a probability.
- 02 / CONTEXT
Which contracts and time?
Save the symbol, expiry scope, quote time, OI date and calculation method. Recheck these before comparing an updated wall.
- 03 / OBSERVATION
What actually happened?
Record a return through the level, continuation beyond it, or no touch. Preserve the earlier snapshot so a later wall cannot rewrite the earlier observation.
Start with the invented ladder below. Then use the same-data comparison checklist before comparing two platforms. A wall is a model output, not a measured order waiting at that strike.
Read the price first, then the exposure
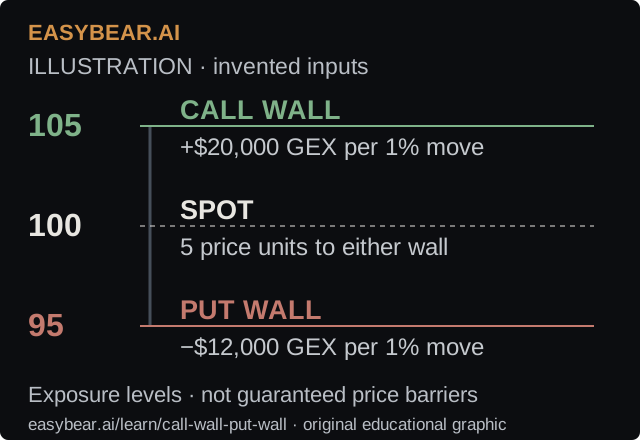
In this fictional example, price is 100. The call wall is 105 and the put wall is 95. Both are five price units away. The exposure tells you the modeled sensitivity at each strike; it is not a price target.
Call wall · 105
+$20,000 GEX per 1% move. Positive modeled gamma: a delta-neutral hedge would sell into rises and buy into falls, with other inputs fixed.
Put wall · 95
−$12,000 GEX per 1% move. Negative modeled gamma: a delta-neutral hedge would sell into falls and buy into rises, with other inputs fixed.
The useful comparison: the call wall has more absolute GEX here ($20,000 versus $12,000). That does not tell you which wall price will reach or whether either will hold. These are model mechanics, not observed dealer trades.
Check the numbers
Distance to call wall: 105 − 100 = 5. Distance to put wall: 100 − 95 = 5. The put-wall exposure magnitude is 12,000 ÷ 20,000 = 60% of the call-wall magnitude. These hypothetical exposure inputs are not derived from a live options chain.
Price crossed a wall. What now?
A crossing tells you where price went, not what it will do next. Compare these two hypothetical crossings, then the no-touch case below.
Returns below the call wall
Continues above the call wall
The third outcome / no interaction
Price never reaches the wall
Record no touch during the observed window. It would be misleading to count this as a wall that “held.” Include this outcome in a session study alongside returns and continuations.
All three paths are teaching illustrations with no specified duration. None establishes how frequently an outcome occurs or why it occurred.
- Check the time and scope. Compare the same ticker and expiry set. An old 0DTE wall and a current Multi-Day wall describe different books.
- Watch the actual price response. Is price returning through the level or staying beyond it? Exposure alone cannot answer this.
- Recheck the updated map. The wall or exposure may change as prices, Greeks and the included contracts change. Open interest generally updates overnight.
- Keep the risk decision separate. Wall distance is not a validated stop distance. The dashboard does not supply an entry, position size or expected win rate.
The same checks apply at a put wall. Touching its strike does not automatically erase negative gamma or make price bounce.
Inspect the current exposure by strike →
Why two dashboards can show different walls
Match the ticker, expiry scope, timestamp and definition before comparing. A provider using a different position assumption or strike window can identify a different level.
0DTE
EasyBear uses the wall from the full selected book of contracts expiring that day.
Multi-Day
EasyBear prioritizes qualifying strikes in its ticker-specific near-spot window. If none qualify there, it falls back to the full-book wall.
A call wall needs positive net GEX at or above spot; a put wall needs negative net GEX at or below spot. No qualifying strike means no wall. Shelves mark other concentrations in the displayed strike window.
Wall, flip and regime are different. A wall is a strike concentration. The gamma flip is a simulated zero crossing. The displayed regime uses current net GEX and the model’s transition band.
Keep the visual reference
Download the ladder (PNG) Vector version (SVG)
Use this original teaching graphic with its illustration label and EasyBear attribution intact. It contains no provider market data. For the arithmetic behind exposure, see the GEX vs DEX worked example.
Mechanics: OIC: Gamma. EasyBear wall-selection rules and data assumptions: methodology. The hypothetical paths above are teaching scenarios, not empirical evidence of wall behavior.
Frequently asked
What is a call wall?
A call wall is a positive net-GEX concentration at or above spot. Multi-Day selects the largest qualifying concentration within the near-spot window, with a full-book fallback when none qualifies nearby. 0DTE uses today's full-book wall. Its dollar value is modeled hedge sensitivity, not measured futures selling or a guaranteed price cap. It is absent if no qualifying strike exists.
What is a put wall?
A put wall is a negative net-GEX concentration at or below spot. Multi-Day selects the most negative qualifying concentration within the near-spot window, with a full-book fallback when none qualifies nearby. 0DTE uses today's full-book wall. Touching its strike does not automatically collapse gamma or cause a reversal. It is absent if no qualifying strike exists.
How do you trade around gamma walls?
Use walls to locate modeled exposure and compare its size, scope and timestamp. Exposure alone does not establish an entry, support or resistance, a breakout outcome or a profitable strategy.